

Celsius recently published its 4Q’25 and FY’25 results. Since we have been invested in Celsius for about a year, I thought this would be a great moment to reflect on our investment.
A lot has happened at Celsius in the last 12 months. When we initiated our position, I would not have expected this much change so quickly. In the span of just one year, the business has become significantly more resilient, revenue streams have been diversified across multiple brands, and Celsius has taken greater control of its distribution after assuming the captaincy of PepsiCo’s energy business.
If I were to plot Celsius on a company lifecycle graph, they have effectively “leapfrogged” from the hyper-growth phase straight into the mature growth phase. Typically, when a company manages to move up a stage—especially when the broader market doesn’t expect it—investors are positioned to capture the best returns.
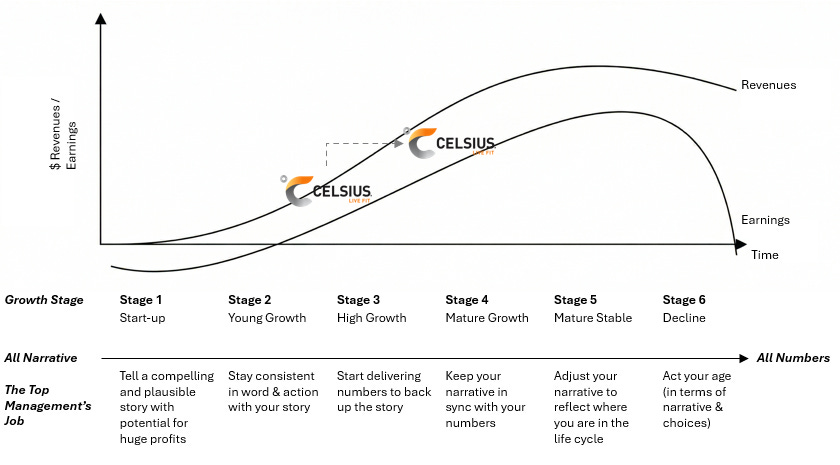
Source: CC
Celsius has firmly cemented itself as the #3 player in the U.S. energy market, and I believe it is here to stay. Now, we get to enjoy the compounding effects of this mature growth phase. While top-line growth will naturally decelerate, profitability is poised to scale materially. At Capital Compounding, we like to fish in this pond.
4Q’25 and FY’25 By the Numbers
First things first, Celsius posted the following highlights:
Revenues: Increased by 117% in 4Q’25 (to $722m) and 86% for FY’25 (from $1.35bn to $2.51bn).
Gross Margin: Decreased from 50.2% in 4Q’24 to 47.4% in 4Q’25. However, for the full year, gross margins expanded 20 bps from 50.2% to 50.4%.
Adjusted EBITDA: Hit $134m in Q4 (+113% y/y) and $620m for FY’25 (+142% y/y).
Adjusted EPS: Reached $0.26 in Q4 (+86% y/y) and $1.34 for FY’25 (+91% y/y).
Market Share: The combined portfolio captured roughly 20% of the U.S. energy market in 4Q’25.
During the Q3 earnings call, management had already warned that Q4 would be messy. Gross margins were expected to take a hit as inventory was physically moved from one distribution network to another (Anheuser-Busch to PepsiCo), resulting in increased logistics costs. Therefore, the margin drop to 47.4% was widely anticipated.
The transition of Alani Nu into the PepsiCo system will be finalized in the coming month, allowing Celsius to shift its focus toward operational efficiencies and scaling the business further.
From hyper growth towards mature growth
Celsius grew its Q4 revenues by an astonishing 117% (from $332m to $722m). However, this was almost entirely driven by the recent acquisition of Alani Nu, which added $370m to the top line.
It is worth noting that Celsius records revenue when PepsiCo takes on inventory, not when the product is sold to the end consumer. This inventory timing is why quarterly revenues were so volatile throughout 2024, ultimately creating the attractive buying opportunity we capitalized on early last year.
(If you are unfamiliar with Celsius, I have written a deep dive here:

The Power of the Portfolio
A lot has changed since our initial purchase, and the share price has roughly doubled. But the underlying business has fundamentally strengthened.
By commanding a portfolio of three distinct brands (Celsius, Alani Nu, and Rockstar Energy), Celsius now has immense leverage with retailers. The risk of losing market share back to Red Bull and Monster has been significantly reduced. Furthermore, the gap between Celsius at #3 and the #4 player is now so wide that it will be incredibly difficult for smaller brands to challenge them. I would not rule out future bolt-on acquisitions in the core energy space to further bolster Rockstar’s position.
In the below table you can find U.S. market share per portfolio:
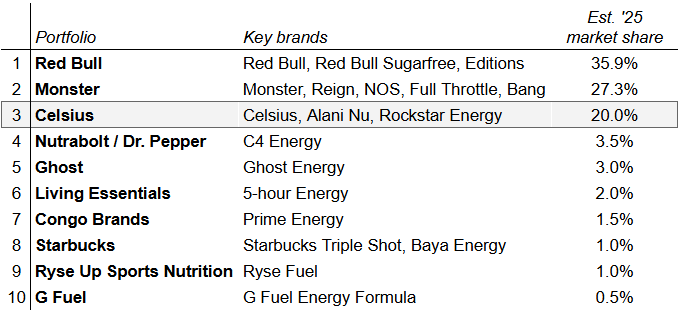
Source: Celsius investor presentation, Circana, NielsenIQ
The top three players hold the majority of the leverage when negotiating shelf space. During the Consumer Analyst Group of New York (CAGNY) conference on February 19th, management highlighted that while negotiations are ongoing, they already expect massive retail gains:
“Coming out of the resets, we anticipate Celsius to gain distribution gains and space gains within our retail footprint by over 17%, and shelf space allocations. And Alani Nu, we anticipate over 100% increase with a significant portion of this space coming from Convenience.” (John Fieldly, CEO, CAGNY, 2026)
Now that Celsius has a multi-brand portfolio, they can optimize promotions. Because the three brands target completely different audiences, they don’t cannibalize each other. For example, they can use Rockstar to run deep volume discounts to capture budget-constrained customers, while maintaining premium pricing and higher margins on Celsius and Alani Nu.
This portfolio approach also allows them to physically block out the competition. During high-traffic periods like the New Year’s fitness rush, Celsius can buy out an entire promotional display. Retailers eagerly agree to this because the brands target diverse demographics (Celsius for mainstream fitness, Alani Nu for wellness-focused females, and Rockstar for legacy energy consumers).
By putting Rockstar and Alani Nu on the front lines of a display, Celsius protects its core brand. It allows Celsius to be the “star,” while Rockstar and Alani act as defensive linemen—capturing overflow traffic and ensuring that every dollar spent goes to Celsius Holdings rather than Monster or Nutrabolt (Keurig Dr. Pepper).
International growth
In Q4, international growth was relatively subdued at just 9% year-over-year. For the full year, international revenues grew +24% to reach ~$93m. I believe this modest Q4 performance was simply because management’s focus and resources were heavily tied up in integrating Alani Nu into the domestic PepsiCo network. I expect international growth to re-accelerate from this year onward.
In November 2025, management brought in PepsiCo veteran Garrett Quigley to run the international business. He boasts a highly successful track record, having previously rolled out Pepsi MAX as a challenger brand against Coca-Cola in Europe.
While we still need to see it translate into the financials, the start of the year has been promising, with Celsius introducing four new flavors overseas. The immediate focus will be building brand awareness and scaling distribution. Over the coming decade, I expect international markets to become a primary growth engine.
Gross margins
If you adjust for the one-time distributor termination fees, Celsius already achieved a highly respectable adjusted EBITDA margin of ~25% in 2025. However, the real profit kicker will come from gross margin expansion.
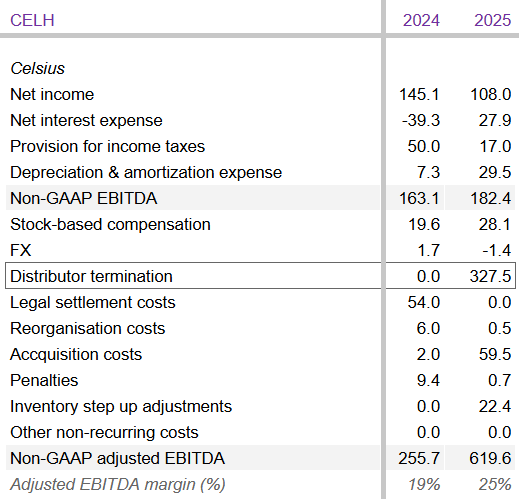
Source: Company reports
Gross margins hovered around 50% in FY’25, but the business has the structural capacity to reach ~55% over time as it scales. Management is targeting 52-53% this year, aiming to reach the mid-50s shortly after:
“Yeah. So I think our target for this year is to get back to the more normalized low-50s. In terms of the opportunity, we do see our ability to move up into the mid-50s like you noted. I wouldn’t necessarily call that a ‘26 target, but definitely in the near-term target into the next handful of years. Some of the things that are going to drive our benefit in order to get back, call it, from the 47.4% that we sat [ph] in Q4 and work our way to the low-50s are really getting the cost of sales or the COGS, the raw material prices in line with what you see with brand CELSIUS. So we are working through that with Alani, and with Rockstar, we’re a bit ahead on Alani. So we should have that cost structure in place by the end of Q1. For Rockstar, we should have that in place by the end of Q2.” (Jarrod Langhans, CFO, 4Q’25)
I leave the valuation part and financial model for the paid subscribers.
Valuation and Conclusion
While significant growth should materialize internationally, I do not factor that into my base valuation to maintain a margin of safety.
Taking a conservative view for the next five years: After the 2026 M&A anniversary, I forecast revenue growth of ~13% in 2027, decelerating to 10% by 2030 (slightly above the projected growth of the broader energy beverage market). Margin expansion will be the primary driver of EPS growth over this period.
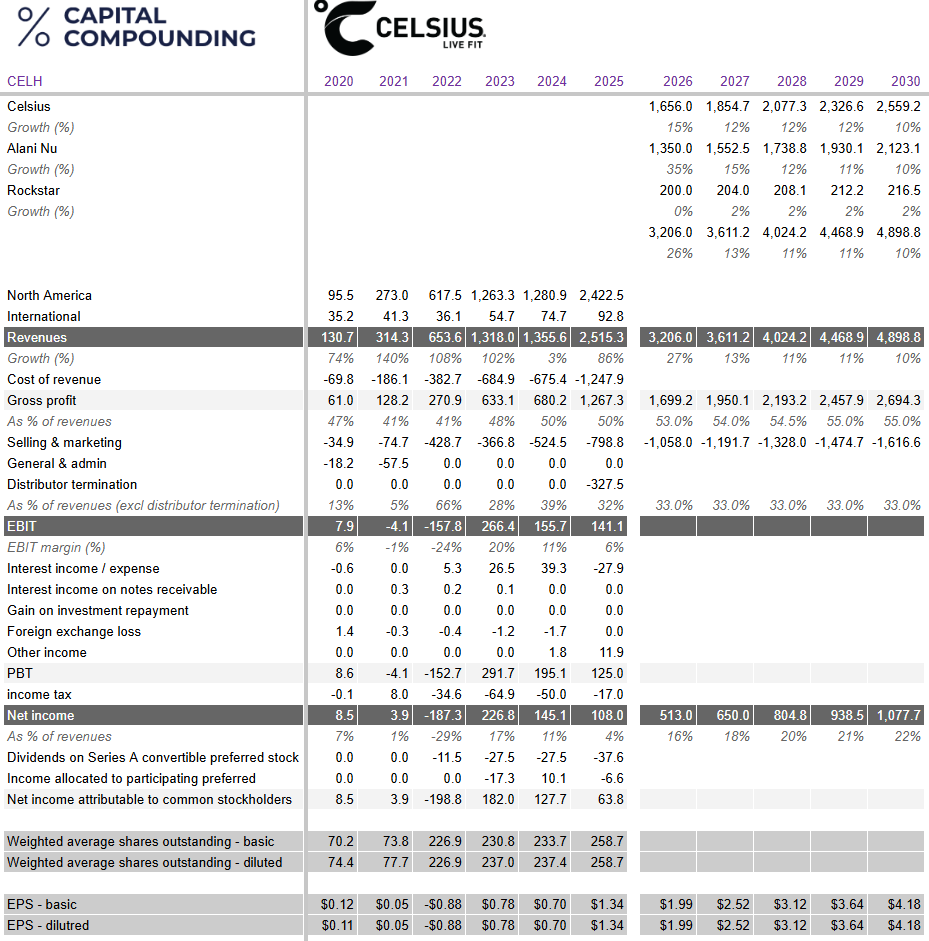
Source: company reports, CC estimates
By ‘30, Celsius should be able to generate roughly $1.1bn in net profit (assuming a ~22% net profit margin derived from a ~30% EBITDA margin). Attaching a reasonable 25x P/E multiple to those earnings yields an estimated IRR of ~14%. To put this into perspective, Monster at ~10% revenues growth, trades at forward P/E multiple of ~38x. One small caveat on the above valuation, I have not taken into account the potential share dilution from the PepsiCo stake. Celsius will however generate enough cash to buy back shares (they already started in Q4) over a 5 year period.
If Celsius can replicate internationally what Monster has achieved (Monster grew its international sales by 27% y/y in recent quarters), this will become a massive compounding machine, and the expected IRR will far exceed 14%. We will be keeping a very close eye on their international execution.
Model: [link]
Disclaimer
The information in this article is provided for informational and educational purposes only. The information is not intended to be and does not constitute financial advice or any other advice, is general in nature, and is not specific to you. Before using this article’s information to make an investment decision, you should seek the advice of a qualified and registered securities professional and undertake your own due diligence. None of the information in this article is intended as investment advice, as an offer or solicitation of an offer to buy or sell, or as a recommendation, endorsement, or sponsorship of any security, company, or fund. The author is not responsible for any investment decision made by you. You are responsible for your own investment research and investment decisions. The author may or may not have shares of the company.